

Fixed-Rate vs. Variable-Rate Mortgage Renewal: How to Choose in Today’s Market
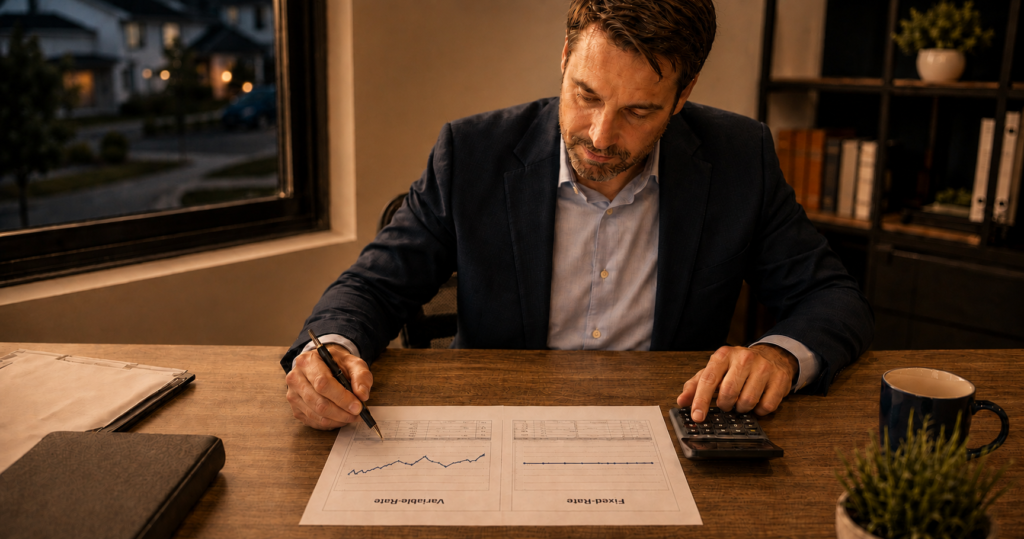
Your mortgage renewal is more than just a date on the calendar. It’s an opportunity to reassess your finances, explore better lending options, and choose a mortgage that aligns with your current lifestyle and future goals. Yet many Canadian homeowners make the same mistake. They receive a renewal notice from their lender, glance at the offered interest rate, sign the paperwork, and move on without considering whether a different mortgage product or lender could better suit their needs. One of the biggest decisions you’ll face during renewal is whether to choose a fixed-rate mortgage or a variable-rate mortgage. While both options can help you finance your home, they offer very different experiences when it comes to monthly payments, interest rate changes, flexibility, and long-term financial planning. There isn’t a one-size-fits-all answer. The right choice depends on your income, financial priorities, comfort with changing interest rates, and plans for the years ahead. Why Your Mortgage Renewal Matters More Than You Think Many homeowners assume that renewing a mortgage is simply a formality. After all, you’ve already been approved once, you’ve made your payments, and your lender has already sent you a renewal offer. But your renewal period is actually one of the few times you have the flexibility to review your mortgage without purchasing a new home. Instead of automatically accepting your lender’s first offer, this is the perfect opportunity to ask important questions: Does my current mortgage still suit my financial goals? Can I qualify for a better interest rate? Should I change my mortgage term? Would another lender offer better flexibility or features? Should I switch from a fixed rate to a variable rate, or vice versa? The answers may be very different today than they were when you first purchased your home. Your income may have changed, your family may have grown, or your financial priorities may have shifted. Taking time to compare your options now could potentially save money over the life of your next mortgage term. Fixed vs. Variable Mortgage Renewal: The Key Differences at a Glance Before diving into the details, here’s a simple comparison of the two mortgage options. Feature Fixed-Rate Mortgage Variable-Rate Mortgage Interest rate Locked in for the term Changes with market conditions Monthly payment Usually predictable May change depending on your mortgage type and interest rates Budgeting Easier to plan Requires more flexibility Protection if rates increase Yes No Benefit if rates decrease No Yes Financial certainty High Moderate Best suited for Homeowners who value stability Homeowners are comfortable with changing rates Although this table highlights the main differences, choosing the right mortgage involves much more than simply comparing interest rates. Choosing a Fixed-Rate Mortgage: When Stability Is Your Priority A fixed-rate mortgage offers one significant advantage that many homeowners value above everything else: certainty. Once your mortgage is renewed, your interest rate remains the same for the entire term. That means you’ll know what to expect each month, making it much easier to manage your household budget. For many families, this predictability provides valuable peace of mind. A fixed-rate mortgage may be worth considering if: You prefer knowing exactly what your mortgage payment will be each month. You’re managing a household budget with childcare, education, or other fixed expenses. You’re approaching retirement and want greater financial certainty. Rising interest rates would put pressure on your monthly finances. You simply don’t enjoy worrying about market fluctuations. Imagine a family that has recently welcomed its first child. Between daycare costs, groceries, insurance, and everyday living expenses, they already have enough financial commitments. Knowing that their mortgage payment won’t change during the next five years can make financial planning much simpler. That predictability is often the biggest reason homeowners choose a fixed-rate mortgage. Benefits of Choosing a Fixed Rate Beyond payment stability, fixed-rate mortgages offer several additional advantages. Since your interest rate remains unchanged throughout the mortgage term, you’re protected if market rates increase. This can provide reassurance during periods of economic uncertainty when borrowing costs are fluctuating. Fixed-rate mortgages also make long-term budgeting easier because your housing costs remain relatively consistent. This stability can be especially valuable for first-time homeowners or anyone who prefers predictable monthly expenses. For homeowners who prioritize financial certainty over the possibility of short-term savings, a fixed-rate mortgage often provides confidence and peace of mind. Things to Keep in Mind While fixed-rate mortgages offer stability, they aren’t always the lowest-cost option over every market cycle. If interest rates decline after you’ve renewed your mortgage, your rate will generally remain the same until your next renewal date. Depending on your lender and mortgage terms, fixed-rate mortgages may also have higher penalties if you decide to break your mortgage before the end of the term. If you think there’s a possibility you’ll sell your home, refinance, or move before your mortgage expires, this is an important factor to consider. The key advantage of a fixed-rate mortgage isn’t necessarily saving the most money. It’s knowing exactly what to expect, regardless of how the market changes. When a Variable-Rate Mortgage May Be the Better Choice While many homeowners value the certainty of a fixed-rate mortgage, others prefer flexibility. A variable-rate mortgage can be an attractive option if you’re comfortable with some uncertainty and want the potential to benefit if interest rates decrease during your mortgage term. Unlike a fixed-rate mortgage, a variable-rate mortgage is tied to your lender’s prime rate, which is influenced by the Bank of Canada’s policy interest rate. If rates change, your mortgage interest rate may also change, depending on the terms of your mortgage. For some homeowners, this flexibility can work in their favour. For others, it may create uncertainty that makes budgeting more difficult. A variable-rate mortgage may be worth considering if: You have room in your monthly budget if interest rates increase. You’re comfortable with market fluctuations. You expect interest rates to remain stable or decrease over time. You may sell your home or refinance before your mortgage term ends. You prefer greater flexibility over
Mortgage Refinance vs. Second Mortgage vs. HELOC: Which Home Equity Option Is Right for You?
Owning a home is one of the biggest financial investments you’ll ever make. As you pay down your mortgage and your property’s value increases, you build home equity, a valuable asset that can help you achieve other financial goals. Whether you’re planning a major home renovation, consolidating high-interest debt, paying for your child’s education, or investing in another property, your home’s equity may provide access to the funds you need. However, deciding how to use that equity isn’t always straightforward. Many Canadian homeowners find themselves comparing three common financing options: mortgage refinancing, a second mortgage, and a Home Equity Line of Credit (HELOC). Although all three allow you to borrow against your home’s value, they work differently and are designed for different financial situations. Choosing the wrong option could result in higher borrowing costs, unnecessary fees, or repayment terms that don’t fit your needs. What is Home Equity? Before comparing your borrowing options, it’s important to understand what home equity actually means. Home equity is the difference between your home’s current market value and the remaining balance on your mortgage. For example, if your home is worth $900,000 and you still owe $500,000 on your mortgage, you have approximately $400,000 in equity. As you continue making mortgage payments and your property’s value increases, your available equity generally grows. Many lenders allow qualified homeowners to borrow against a portion of this equity, subject to lending guidelines and approval. Three Common Ways to Access Your Home Equity Although all three financing options use your home’s equity, they serve different purposes. Feature Mortgage Refinance Second Mortgage HELOC Receive funds as One lump sum One lump sum Borrow as needed Keeps existing mortgage? No, replaces it Yes Yes Interest rate Often lower Usually higher Variable in most cases Repayment New mortgage payments Separate monthly payments Flexible repayment during draw period Best for Large planned expenses Borrowing without changing current mortgage Ongoing or unpredictable expenses The right choice depends on how much money you need, how quickly you need access to it, your current mortgage terms, and your long-term financial plans. What Is a Mortgage Refinance? Mortgage refinancing involves replacing your existing mortgage with a new one. The new mortgage pays off your current loan while allowing you to borrow additional money based on the equity you’ve built. For example, imagine you currently owe $350,000 on your mortgage, but your home is now worth $700,000. Instead of simply continuing with your existing mortgage, you may refinance for a larger amount, such as $450,000. The first $350,000 pays off your original mortgage, while the remaining $100,000 is provided to you for other financial needs. Because refinancing replaces your original mortgage, you’ll receive a completely new mortgage agreement with updated interest rates, repayment terms, and amortization period. When Does Mortgage Refinancing Make Sense? Refinancing is often a good option when you need a significant amount of money for a planned expense. Many homeowners refinance to: Complete major home renovations. Consolidate high-interest debt into one lower-interest payment. Finance large investments. Purchase another property. Pay education expenses. Access equity for long-term financial planning. Refinancing can also be attractive if current mortgage rates are favourable compared to your existing mortgage, although it’s important to consider any penalties for breaking your current mortgage early. Advantages of Mortgage Refinancing One of the biggest advantages of refinancing is that it often offers some of the lowest borrowing rates available because the loan is secured by your home. It also combines everything into one monthly mortgage payment, making budgeting easier for many homeowners. Since the repayment period can extend over many years, monthly payments may remain relatively manageable even when borrowing a substantial amount. Things to Consider Refinancing isn’t always the right solution. If you’re still in the middle of your mortgage term, your lender may charge a prepayment penalty for ending your existing mortgage early. You’ll also need to qualify for the new mortgage based on your income, credit history, and overall financial situation. For homeowners who only need a smaller amount of money, refinancing the entire mortgage may not be the most practical option. What Is a Second Mortgage? A second mortgage is exactly what its name suggests. Instead of replacing your existing mortgage, it adds another loan that is secured against the same property. Your first mortgage remains exactly as it is, including its interest rate and remaining term. The second mortgage becomes an additional loan with its own repayment schedule. This option is often chosen by homeowners who have a favourable interest rate on their first mortgage and don’t want to lose it by refinancing. When Is a Second Mortgage a Good Choice? A second mortgage may be appropriate if you need access to equity but prefer not to refinance your existing mortgage. Common reasons include: Consolidating debt. Covering unexpected expenses. Funding business opportunities. Paying for major repairs. Managing temporary financial challenges. Because the original mortgage stays untouched, homeowners avoid breaking their current mortgage contract and any associated penalties. Advantages of a Second Mortgage The biggest benefit is preserving your existing mortgage. If your current mortgage has a very low interest rate, replacing it through refinancing may not make financial sense. A second mortgage allows you to keep that favourable rate while still accessing additional funds. Approval may also be faster in certain situations, especially when compared to refinancing an entire mortgage. Things to Consider Second mortgages generally carry higher interest rates than first mortgages because they represent a greater risk to lenders. You’ll also have two separate loan payments to manage, which may affect your monthly budget. For this reason, it’s important to ensure the additional payment comfortably fits within your financial plan. What Is a HELOC? A Home Equity Line of Credit (HELOC) works differently from both refinancing and a second mortgage. Instead of receiving one large lump sum, you’re approved for a credit limit that allows you to borrow only what you need, when you need it. It functions similarly to a credit line. As you
Commercial Mortgage vs. Small Business Loan: Which Is Better for Financing Commercial Property in Canada?
Buying commercial property is a major investment for any business owner. Whether you’re purchasing an office, retail space, warehouse, medical clinic, or mixed-use building, choosing the right financing can have a significant impact on your cash flow, borrowing costs, and long-term financial success. Two of the most common financing options in Canada are commercial mortgages and small business loans. While both can help fund business growth, they serve different purposes and have different qualification requirements, repayment terms, and borrowing limits. In most cases, a commercial mortgage is the preferred option for purchasing or refinancing commercial real estate because it offers larger loan amounts, longer repayment periods, and competitive interest rates. A small business loan, on the other hand, is often better suited for equipment purchases, renovations, inventory, or short-term financing needs. Key Takeaways Commercial mortgages are specifically designed to purchase, refinance, or construct commercial properties. Small business loans provide flexible financing for equipment, inventory, renovations, working capital, and some smaller property purchases. Commercial mortgages generally offer lower interest rates because the property serves as collateral. Small business loans typically have shorter repayment terms but may provide faster approvals. Commercial mortgage down payments in Canada usually range from 20% to 35%, depending on the property and lender. Commercial mortgage approval focuses on both the property’s value and your business finances, while small business loans place greater emphasis on business cash flow and creditworthiness. What Is a Commercial Mortgage? A commercial mortgage is a loan secured by commercial real estate. Businesses and investors use these loans to purchase, refinance, or develop income-producing or owner-occupied commercial properties. Commercial properties commonly financed through commercial mortgages include: Office buildings Retail plazas Shopping centres Warehouses Industrial buildings Medical and dental clinics Mixed-use properties Apartment buildings Multi-family residential buildings Self-storage facilities Because the property acts as security for the loan, lenders can offer higher borrowing amounts and longer repayment periods than most business loans. Commercial mortgages in Canada commonly feature: Loan amounts from several hundred thousand dollars to millions of dollars Amortization periods of 15 to 25 years Fixed or variable interest rate options Flexible repayment structures based on the property’s use and income For investment properties, lenders carefully assess the property’s ability to generate rental income. For owner-occupied properties, they focus more on the financial strength of the business. What Is a Small Business Loan? A small business loan is a flexible financing solution designed to support various business expenses. Unlike a commercial mortgage, these loans are not limited to real estate purchases. Businesses commonly use small business loans for: Equipment purchases Business renovations Inventory Technology upgrades Hiring staff Marketing expenses Working capital Business expansion Some lenders also allow small business loans to help finance smaller commercial property purchases, although borrowing limits are generally much lower than commercial mortgages. Many Canadian businesses also access financing through government-supported programs that help eligible businesses obtain funding with lender support. Repayment terms usually range from one to ten years, making these loans better suited for shorter-term financing needs. Commercial Mortgage vs. Small Business Loan Feature Commercial Mortgage Small Business Loan Primary Purpose Purchase or refinance commercial property Business expenses and smaller financing needs Loan Amount High Moderate Interest Rates Usually lower Usually higher Repayment Period 15 to 25 years 1 to 10 years Collateral Commercial property May be secured or unsecured Down Payment Usually 20% to 35% Often lower or not required Approval Focus Property value, income, and business financials Business revenue, cash flow, and credit history Closing Timeline Approximately 4 to 8 weeks A few days to several weeks When Does a Commercial Mortgage Make Sense? A commercial mortgage is generally the better choice when you’re purchasing or refinancing commercial real estate that you plan to own over the long term. This financing option is ideal for businesses such as: Medical and dental practices purchasing their clinic Retail businesses buying their storefront Manufacturers purchasing industrial space Investors acquiring rental commercial properties Professional offices purchasing office buildings Businesses expanding into larger facilities Commercial mortgages typically provide: Higher borrowing limits Longer repayment periods Lower monthly payments due to longer amortization Competitive interest rates Opportunities to build equity in commercial real estate Although approval usually takes longer because lenders require property appraisals, financial reviews, and legal due diligence, the long-term financial benefits often outweigh the additional documentation. When Does a Small Business Loan Make Sense? A small business loan may be the better option when your financing needs are smaller, temporary, or unrelated to purchasing commercial property. Businesses often choose a small business loan when they need financing for: Office renovations Leasehold improvements Equipment purchases Furniture Inventory Technology upgrades Cash flow management Seasonal operating expenses Small business loans can also benefit newer businesses that may not yet qualify for a traditional commercial mortgage due to limited operating history. Because the approval process is generally simpler, funding is often available much faster than commercial mortgage financing. Down Payment Requirements Commercial mortgage down payment requirements depend on several factors, including the property’s location, condition, intended use, and the lender’s risk assessment. In Canada, borrowers should generally expect to contribute between 20% and 35% of the property’s purchase price. Owner-occupied commercial properties often qualify for lower down payment requirements because the business itself occupies the property. Investment properties may require a larger equity contribution. Small business loans vary significantly. Some unsecured loans require no down payment, while secured loans may require collateral instead of a traditional property down payment. How Do Lenders Qualify a Commercial Mortgage? Commercial mortgage approval considers both the borrower and the property. Lenders commonly review: Property appraisal Property location Net Operating Income (NOI) Debt Service Coverage Ratio (DSCR) Business financial statements Corporate tax returns Personal credit history Existing business debt Business experience Available down payment For income-producing properties, lenders want to see that rental income is sufficient to cover mortgage payments and operating expenses. Understanding DSCR The Debt Service Coverage Ratio (DSCR) measures whether a property’s income is enough to cover its debt obligations. A stronger DSCR indicates lower
How Adjustable-Rate Mortgages Can Impact Your Long-Term Financial Goals
Buying a home is one of the largest financial commitments most Canadians will ever make. While many borrowers focus on securing the lowest interest rate available, the type of mortgage they choose can have a lasting impact on their financial future. An adjustable-rate mortgage is one option that can offer flexibility and lower initial borrowing costs, but it can also introduce uncertainty that affects long-term planning. For some homeowners, an adjustable-rate mortgage can create opportunities to save money and improve cash flow. For others, changing interest rates may create challenges that affect budgeting, investing, retirement planning, and overall financial stability. Understanding both sides of the equation is essential before making a decision. Whether you are buying your first home, refinancing an existing mortgage, renewing your mortgage, or investing in real estate, knowing how an adjustable-rate mortgage fits into your financial strategy can help you make a more informed choice. This guide explains how adjustable-rate mortgages work, their advantages and disadvantages, and how they can influence your long-term financial goals. What Is an Adjustable-Rate Mortgage? An adjustable-rate mortgage is a mortgage where the interest rate changes when the lender’s prime rate changes. Unlike a fixed-rate mortgage, which maintains the same interest rate throughout the term, an adjustable-rate mortgage moves with market conditions. In Canada, adjustable-rate mortgages are typically linked to the lender’s prime lending rate. When the prime rate increases, the mortgage rate may increase. When the prime rate decreases, the mortgage rate may decrease. This structure means borrowers can benefit when interest rates fall, but they also face the possibility of higher borrowing costs when rates rise. Understanding this relationship is crucial because even small interest rate changes can affect your financial plans over time. How Does an Adjustable-Rate Mortgage Work? Many borrowers ask, “How does an adjustable-rate mortgage work?” The answer is relatively simple. Most lenders offer adjustable-rate mortgages as a percentage above or below their prime rate. For example, a lender may offer a mortgage at prime minus a certain percentage. If the prime rate changes, the mortgage rate changes as well. Depending on the mortgage structure, the monthly payment may remain the same while the amount applied to principal and interest changes. In other cases, the monthly payment itself may increase or decrease. Because rates can move throughout the mortgage term, borrowers must be comfortable with some degree of uncertainty. This flexibility can create opportunities, but it also requires careful planning. Why Adjustable-Rate Mortgages Have Become Popular Housing affordability remains a major concern for many Canadians. Rising home prices have made it more difficult for buyers to qualify for mortgages and manage monthly housing expenses. Because adjustable-rate mortgages often begin with lower rates than comparable fixed-rate mortgages, they can provide immediate savings. Lower borrowing costs may help borrowers qualify for larger mortgage amounts or maintain more manageable monthly payments. For homeowners who understand the risks and have a strong financial plan, these potential savings can be used to support larger financial goals. However, focusing only on the initial rate without considering future changes can create challenges later. How Adjustable-Rate Mortgages Affect Long-Term Financial Planning A mortgage is not just a monthly payment. It is a financial commitment that can influence nearly every aspect of your financial future. Long-term financial goals often include building home equity, saving for retirement, investing in real estate, paying for education, growing wealth, and achieving financial independence. The type of mortgage you choose can directly affect your ability to accomplish these goals. Because adjustable-rate mortgages can change over time, they require borrowers to think beyond today’s interest rates and consider how future changes may impact their overall financial picture. The Benefits of Adjustable-Rate Mortgages for Long-Term Goals Lower Initial Mortgage Costs One of the most significant advantages of an adjustable-rate mortgage is the potential for lower initial borrowing costs. A lower mortgage rate often means lower monthly payments during the early years of homeownership. This additional cash flow can be directed toward savings, investments, debt reduction, or emergency funds. For borrowers with disciplined financial habits, this flexibility can accelerate progress toward important financial objectives. Greater Cash Flow for Investments Many homeowners use the savings from lower mortgage payments to invest elsewhere. Instead of directing all available income toward housing costs, borrowers may contribute more to retirement accounts, tax-advantaged savings plans, investment portfolios, or business ventures. Over time, these investments may generate returns that exceed the mortgage interest savings available through other mortgage structures. Faster Wealth Building Opportunities When managed strategically, lower mortgage costs can create opportunities for wealth accumulation. Some homeowners use the monthly savings to make additional principal payments on their mortgage. Others invest the difference to build long-term assets. Either approach can contribute to stronger financial outcomes when combined with consistent financial planning. Also Read: Everything You Need to Know About 50-Year Mortgages in Canada The Risks of Adjustable-Rate Mortgages Rising Interest Rates Can Increase Costs The biggest risk associated with an adjustable-rate mortgage is the possibility of rising interest rates. When rates increase, borrowing costs rise as well. This can affect monthly affordability and reduce the amount of money available for other financial priorities. Homeowners who have not prepared for rate increases may find themselves adjusting budgets or postponing financial goals. Long-Term Budgeting Becomes More Difficult One of the biggest advantages of a fixed-rate mortgage is predictability. Borrowers know exactly what to expect throughout the mortgage term. With an adjustable-rate mortgage, future costs are less certain. This can make long-term budgeting more challenging, particularly for households with fixed incomes or limited financial flexibility. Successful financial planning often depends on creating realistic expectations for future expenses. Reduced Savings Potential During Higher Rate Cycles When interest rates rise significantly, homeowners may need to dedicate a larger portion of their income toward housing expenses. This can reduce contributions to savings accounts, retirement plans, investment portfolios, and other financial goals. Over time, these missed opportunities can affect overall wealth accumulation. Adjustable-Rate Mortgage vs Fixed-Rate Mortgage One of the most common mortgage questions in
Everything You Need to Know About 50-Year Mortgages in Canada
For many Canadians, rising home prices continue to make homeownership more challenging. Higher property values, interest rates, and stricter qualification requirements have encouraged borrowers to explore alternative financing options. One mortgage option that often generates interest is the 50-year mortgage. Many homebuyers are attracted to the idea of lower monthly payments and increased affordability. However, before considering this type of mortgage structure, it is important to understand how it works, whether it is available in Canada, and what long-term financial impact it can have. This guide explains everything you need to know about a 50-year mortgage in Canada, including how it works, its advantages and potential drawbacks, and alternatives that may better suit your financial goals. What Is a 50-Year Mortgage? A 50-year mortgage refers to a mortgage with a 50-year amortization period. Amortization is the total length of time required to pay off a mortgage completely through regular payments. In a traditional mortgage, the amortization period is commonly 25 years. Some lenders may offer longer amortization periods in specific circumstances. With a 50-year amortization, the repayment of the principal balance is spread over five decades instead of 25 years. Because the repayment period is much longer, monthly mortgage payments are typically lower. This can make homeownership appear more affordable in the short term. However, borrowers must understand that lower monthly payments often come at a high long-term cost. How Does a 50-Year Mortgage Work in Canada? A mortgage payment consists of both principal and interest. When a mortgage is stretched over a longer amortization period, each payment includes a smaller amount of principal repayment. As a result, borrowers benefit from reduced monthly obligations. However, interest continues to accumulate over a much longer period. This means that the total amount paid over the life of the mortgage can increase substantially. For example, if two borrowers have the same mortgage amount but different amortization periods, the borrower with the longer amortization may enjoy lower monthly payments but will likely pay considerably more interest over time. Understanding how a 50-year mortgage works in Canada requires looking beyond the monthly payment and considering the overall financial picture. Also read: How Long Do You Need to Be Self-Employed to Get a Mortgage in Canada? Are 50-Year Mortgages Available in Canada? This is one of the most common questions borrowers ask. Currently, traditional insured mortgages in Canada are subject to federal mortgage lending guidelines. In most situations, insured mortgages have maximum amortization limits that are significantly shorter than 50 years. However, certain private lending arrangements or specialized financing solutions may offer extended amortization structures under specific circumstances. These options are generally not available through every lender and often involve different qualification requirements, higher interest rates, or additional lender scrutiny. Borrowers exploring long amortization mortgage options should work with experienced mortgage professionals who have access to a broad network of lenders and financing solutions. Mortgage brokers can help determine what options may be available based on individual financial circumstances and property type. Why Do Borrowers Consider a 50-Year Mortgage? The primary reason borrowers explore longer amortization periods is affordability. As housing prices continue to increase in many Canadian markets, monthly mortgage payments can place significant pressure on household budgets. A longer repayment period can reduce monthly payments and create additional cash flow flexibility. For some borrowers, this flexibility may allow them to purchase a home sooner than they otherwise could. Others may use the reduced monthly payment to manage other financial obligations, invest, or maintain emergency savings. While these advantages can be appealing, it is important to weigh them carefully against the long-term costs. Benefits of a 50-Year Mortgage Lower Monthly Mortgage Payments The most obvious advantage is the reduction in monthly mortgage payments. By extending repayment over a longer period, borrowers spread the loan balance across more payments. This can make homeownership more manageable, especially during periods of higher interest rates or elevated housing prices. For buyers struggling to qualify based on monthly debt obligations, lower payments may improve affordability calculations. Improved Cash Flow Many homeowners value flexibility in their monthly budgets. Lower mortgage payments can leave more money available for daily expenses, savings goals, home improvements, education costs, or investment opportunities. This additional cash flow may provide financial breathing room during uncertain economic conditions. Easier Entry Into the Housing Market For some first-time buyers, longer amortization periods can make entering the housing market possible when shorter amortizations create payments that exceed their budget. Although affordability should always be evaluated carefully, some borrowers view extended amortization as a tool that helps them secure a property while maintaining manageable monthly expenses. Drawbacks of a 50-Year Mortgage Significantly Higher Interest Costs The largest disadvantage of a 50-year mortgage is the amount of interest paid over time. Because the mortgage balance remains outstanding for much longer, interest continues to accumulate for decades. In many cases, borrowers may pay substantially more than they originally borrowed. This is often the single most important factor to consider when evaluating a long amortization mortgage in Canada. Slower Equity Growth Home equity represents the portion of the property that the homeowner truly owns. With a shorter amortization period, more of each payment goes toward reducing the principal balance. With a 50-year mortgage, principal repayment occurs much more slowly. As a result, homeowners build equity at a slower pace and may take significantly longer to achieve meaningful ownership in their property. Greater Long-Term Financial Commitment A 50-year amortization extends mortgage repayment across a substantial portion of a person’s lifetime. Although borrowers can often make additional payments or refinance later, committing to such a long repayment schedule may limit future financial flexibility. Life circumstances can change dramatically over several decades, making long-term planning particularly important. Who Might Benefit From a Long Amortization Mortgage? Long amortization mortgages are not appropriate for every borrower. However, they may be considered by individuals who prioritize lower monthly payments and have a clear understanding of the long-term costs involved. Potential candidates may include: First-time homebuyers facing affordability challenges Self-employed
How to Get Approved for a Mortgage With a Consumer Proposal or Bad Credit in Canada
Yes, you can get approved for a mortgage in Canada with a consumer proposal or bad credit, but lenders will charge higher interest rates, require a larger down payment, and demand extensive financial documentation. Most major Canadian lenders will approve mortgages after a consumer proposal is paid off or within 2 years of completion. Bad credit borrowers can qualify through alternative lenders, B-lenders, or mortgage brokers specializing in bad credit mortgages. Your approval odds depend on how much time has passed since the negative credit event, your current financial stability, and the strength of your compensating factors. Understanding Consumer Proposals and Their Impact on Mortgages A consumer proposal is a formal debt restructuring arrangement with creditors, administered by a Licensed Insolvency Counselor. Instead of filing bankruptcy, you propose to repay a portion of your debt over a set period (typically 5 years). This is viewed more favorably by lenders than bankruptcy, but still represents financial distress. Consumer proposals remain on your credit report for 6 years after completion. Most Canadian lenders will not approve traditional mortgages while the proposal is active. However, some specialized lenders do approve mortgages to borrowers with active consumer proposals if you’ve demonstrated consistent payments and have other strong financial indicators. Once your proposal is paid off, your mortgage approval odds improve dramatically. You can typically qualify for a mortgage with a major Canadian lender within 2 years of completion. By year 3 and beyond, approval becomes much easier with potentially better rates. Bad Credit Explained: Credit Scores and Mortgage Approval In Canada, credit scores range from 300 to 900. Lenders typically categorize borrowers as follows: Credit Score Range Category Mortgage Approval Odds 740+ Excellent Very high with best rates 680 to 739 Good High approval odds 620 to 679 Fair Moderate approval, higher rates 580 to 619 Poor Limited options, much higher rates Below 580 Bad Very limited options, highest rates A score below 620 qualifies as bad credit in Canada. Most traditional banks require minimum scores of 620 to 680. Bad credit borrowers must use alternative lenders, B-lenders, or mortgage brokers with access to specialized networks. Mortgage Options for Bad Credit and Consumer Proposal Borrowers Traditional Banks Royal Bank, TD, BMO, and Scotia Bank rarely approve mortgages for active consumer proposal borrowers. However, if your proposal is paid off and you have 2+ years of clean payment history after completion, these lenders become viable options. You’ll pay higher interest rates (typically 1 to 2.5% above prime), require a larger down payment (20%+), and face stricter documentation requirements. Credit Unions Credit unions across Canada are often more flexible with bad credit and consumer proposal applicants. Ontario, BC, and Alberta credit unions frequently approve mortgages with credit scores as low as 600. They typically charge 0.5 to 1.5% above prime and may accept down payments of 15 to 20%. Mortgage Brokers Mortgage brokers specialize in matching bad credit and consumer proposal borrowers with appropriate lenders. They have relationships with multiple lenders willing to work with challenging credit histories. Brokers can often negotiate better rates than you’d get by approaching lenders directly. B-Lenders B-lenders bridge traditional banking and private lending. They approve mortgages for borrowers with bad credit, consumer proposals, or other credit challenges. Interest rates range from 4.5% to 7%, which is higher than traditional rates but lower than those of private lenders. Many B-lenders require 15 to 20% down. Private Mortgage Lenders Private lenders offer mortgages regardless of credit history or active consumer proposals. The trade-off is significant: interest rates typically range from 6% to 10%, terms are shorter (1 to 3 years), and fees are substantial. Use private lending as a stepping stone to rebuild credit and qualify for better rates later. Insured Mortgages with Down Payment Assistance Some lenders approve borrowers with bad credit through insured mortgages if the credit issues are compensated by high current income and stable employment. Mortgage insurance adds 2 to 4% to your mortgage costs but makes approval possible with lower down payments. Also read: Commercial vs. Residential Mortgages: What’s the Difference? Mortgage Approval Strategies for Bad Credit and Consumer Proposals 1. Maximize Your Down Payment The single most effective way to offset bad credit or an active consumer proposal is a large down payment. A 20% to 25% down payment dramatically improves approval odds and interest rates. Even a jump from 15% to 20% down changes lender perception significantly. 2. Demonstrate Payment Stability Post-Consumer Proposal If your consumer proposal is active or recently completed, your strongest asset is proof of consistent, on-time payments during and after the proposal period. Provide documentation showing 12+ months of proposal payments made on time. This demonstrates commitment to honoring financial obligations. 3. Build Current Financial Strength Beyond past credit problems, show lenders your current financial position is strong. Maintain high savings (ideally 3+ months of mortgage payments reserved). Demonstrate steady employment with 2+ years at the same employer. Keep the debt-to-income ratio below 40%. 4. Improve Your Credit Score Before Applying If time permits, spend 6 to 12 months improving your credit before mortgage shopping. Pay all bills on time. Reduce outstanding debt. Dispute any errors on your credit report with the credit bureaus. Even a 20 to 40-point score improvement opens new lender options. 5. Use a Co-Signer or Co-Applicant Adding a spouse or family member with good credit to your application substantially improves approval odds and rates. Their credit score and income help offset your negative history. This is particularly effective if they’re your spouse, as their income strengthens the application. 6. Provide Written Explanation Lenders want context for bad credit or consumer proposals. Write a brief, professional explanation addressing what caused your credit problems (job loss, medical emergency, divorce) and what steps you’ve taken to prevent recurrence. This humanizes your application and shows accountability. 7. Gather Comprehensive Financial Documentation Beyond standard mortgage documents, compile evidence of financial stability: job letters confirming employment and salary, 2+ months of recent pay stubs, 3+ months of bank statements, proof of
Can I Get an Ontario Mortgage If I Am Self-Employed With Inconsistent Income?
Yes, you can get an Ontario mortgage as a self-employed individual with inconsistent income. Still, you’ll face stricter documentation requirements, higher interest rates, and lower approval odds compared to salaried employees. Most Ontario lenders require 2 years of consistent tax returns and financial statements to verify income stability. Alternative lenders and mortgage brokers specialize in self-employed mortgages and may approve you with a longer income history or compensating factors. The Challenge of Self-Employment and Mortgage Approval Self-employed borrowers in Ontario encounter significantly more scrutiny from traditional lenders. Banks and mortgage institutions view inconsistent income as higher risk because it’s unpredictable, making it harder to guarantee you’ll reliably make monthly payments. Unlike salaried employees who provide a pay stub showing stable income, self-employed individuals must prove income through tax documents spanning multiple years. The inconsistency problem is compounded if you’re in a newer business or your income fluctuates seasonally. A freelance marketer earning $80,000 one year and $45,000 the next signals risk to lenders. Even if your current year’s income is high, they want assurance that this income level will persist throughout the mortgage term. Income Documentation Requirements for Self-Employed Borrowers Ontario lenders typically require the following documentation from self-employed applicants: Tax Returns Most traditional lenders require 2 years of personal tax returns (Notice of Assessment). Some specialized lenders may accept 1 year, but this limits your options significantly. Your tax returns must match the income you claim on your mortgage application, and the Canada Revenue Agency will verify these directly. Financial Statements Accountant-prepared financial statements showing profit and loss are essential. These demonstrate how much profit your business generates after expenses. Unaudited statements are acceptable, but the more comprehensive the statements, the stronger your application. Business Bank Statements Many lenders request 3 to 6 months of current business bank statements. These show active business transactions and help verify the income you’ve claimed on your tax returns. Business License and Registration Proof that your business is legitimately registered and operating (business license, corporate registration, sole proprietorship documents) strengthens your application. Canada Revenue Agency MyBusiness Account Some lenders request access to your CRA account to verify business income directly. This adds transparency and reduces documentation fraud risk. Income Averaging and Calculation Methods Lenders calculate self-employed income differently from salaried income. They typically use income averaging across multiple years to smooth out inconsistencies. Two-Year Average Method: The most common approach. If you earned $70,000 in Year 1 and $90,000 in Year 2, lenders may use $80,000 as your qualifying income. This method protects against year-to-year swings while still reflecting your actual earning capacity. Declining Income Rule: If your income has declined over the past two years, some lenders will use only the most recent year’s income as your qualifying amount. This conservative approach assumes downward trends continue. Best Year Method: Alternative lenders sometimes use your highest-earning year within the past two years. This is less common but available if you can demonstrate strong justification for lower recent years (market downturn, business transition, etc.). Mortgage Options for Self-Employed Borrowers in Ontario Traditional Banks Major banks (RBC, TD, BMO, Scotia) do approve self-employed mortgages, but with strict criteria. You’ll typically need 2 years of strong, consistent tax returns showing increasing or stable income. Interest rates may be 0.25% to 0.75% higher than for comparable salaried applicants. Approval odds are lower, and the process takes longer. Credit Unions Ontario credit unions often have more flexible self-employed lending policies than big banks. They may accept a shorter income history (1 year) or be more flexible with income documentation. Rates are sometimes more competitive, and approval timelines are faster. Mortgage Brokers Mortgage brokers have access to multiple lenders and specialize in self-employed deals. They understand which lenders are currently accepting self-employed applications and can match your profile to appropriate options. Brokers are particularly valuable if you’ve been rejected by banks. Alternative Lenders Private mortgage lenders and non-traditional institutions offer self-employed mortgages with more flexible criteria. The trade-off: significantly higher interest rates (often 6% to 10%) and shorter terms. These are useful as temporary solutions while you build stronger financial documentation for a traditional refinance. B-Lenders B-lenders bridge the gap between traditional banks and private lenders. They accept self-employed borrowers with weaker documentation but charge higher rates (typically 4% to 6%) than traditional lenders. Many also offer second mortgages for self-employed applicants. Strategies to Strengthen Your Self-Employed Mortgage Application 1. Show Consistent or Growing Income If your income has grown or remained stable over 2 years, emphasize this. Document the reasons for any dips (market downturn, business restructuring). Lenders prefer upward trends. 2. Maximize Your Down Payment A larger down payment (20% or more) reduces lender risk significantly. Many self-employed borrowers with modest down payments are rejected, but those with 25% to 30% down are approved more easily. If possible, save aggressively before applying. 3. Maintain Excellent Credit Self-employed borrowers must offset income uncertainty with strong credit. Aim for a score of 720 or higher. Pay bills on time, minimize debt, and keep credit utilization below 30%. A spotless credit history compensates for income inconsistency. 4. Reduce Existing Debt Lenders calculate your debt service ratios, which measure how much of your income goes to existing debt payments. Lower existing debt improves your ability to qualify for a mortgage. Pay down credit cards and personal loans before applying. 5. Work with an Accountant A professional accountant improves your application’s credibility. Their financial statements and tax optimization strategies signal professionalism and accurate record-keeping. This is worth the investment for mortgage purposes. 6. Consider a Co-Signer If a family member with stable salaried income co-signs your mortgage, approval odds improve substantially. Their income and credit help offset your self-employment risk. 7. Gather Business Documentation Beyond tax returns, compile evidence of your business stability: client contracts, letters from major clients confirming work, business awards, professional certifications, proof of business longevity. This contextual evidence strengthens your profile. Also read: Can You Get A Mortgage With Debt in Canada? Income Inconsistency: What Lenders Actually
Can You Get A Mortgage With Debt in Canada?
Many Canadians dream of buying a home, but existing debt often creates uncertainty during the mortgage process. Whether it’s credit card balances, student loans, car payments, or a line of credit, borrowers frequently worry that carrying debt will automatically prevent them from qualifying for a mortgage. The good news is that having debt does not necessarily mean you will be denied a mortgage in Canada. In fact, many homeowners successfully qualify for mortgages while managing different types of debt. What lenders truly care about is whether your debt is manageable within your overall financial situation. Mortgage lenders evaluate factors such as your income, credit score, employment stability, monthly expenses, and debt repayment history before making a decision. Understanding how these factors work together can help you prepare for the mortgage application process and improve your approval chances. Here, we’ll explain how debt affects mortgage approval in Canada, what lenders look for, and how you can strengthen your financial profile before applying. Can You Get a Mortgage With Debt? Yes, you can absolutely get a mortgage with debt in Canada. Carrying debt is very common, and lenders understand that many borrowers have financial obligations such as student loans, vehicle financing, or credit cards. Mortgage approval is not about being completely debt-free. Instead, lenders want to see that: Your debt is under control You make payments consistently Your income supports your monthly obligations You manage credit responsibly For example, someone earning a stable income with manageable monthly debt payments may still qualify for a mortgage even if they carry credit card or student loan balances. On the other hand, borrowers with excessive debt, missed payments, or high credit utilization may face more challenges during approval. How Canadian Lenders Evaluate Mortgage Applications When you apply for a mortgage, lenders assess your overall financial health to determine whether you can comfortably afford homeownership costs. They typically review several important factors before approving a loan. Income and Employment Stability One of the first things lenders examine is your income. Stable and reliable employment helps demonstrate that you can consistently make mortgage payments. Lenders may consider: Full-time employment history Self-employment income Additional income sources Length of employment Borrowers with steady income often have stronger approval chances, even if they currently carry debt. Credit Score Your credit score plays a major role in mortgage approval. It gives lenders insight into how responsibly you’ve managed borrowed money in the past. A higher credit score may help you: Qualify for better interest rates Access more mortgage options Improve approval chances Missed payments, collections, and high credit card balances can negatively impact your score and make mortgage approval more difficult. Existing Debt Obligations Lenders look beyond the total amount of debt and focus more on your monthly payment obligations. This may include: Credit card payments Car loans Student loans Personal loans Lines of credit Even if your debt balance is large, manageable monthly payments may still allow you to qualify. Down Payment Amount Your down payment also influences lender risk. A larger down payment can: Reduce the amount you need to borrow Improve approval chances Lower mortgage insurance costs Potentially secure better rates Saving for a higher down payment can sometimes offset concerns about existing debt. Understanding Debt-to-Income Ratios One of the most important parts of mortgage approval is your debt-to-income ratio, commonly measured in Canada using: Gross Debt Service (GDS) Total Debt Service (TDS) These ratios help lenders determine how much of your income goes toward housing and debt payments. Gross Debt Service (GDS) GDS measures the percentage of your income needed to cover housing costs, including: Mortgage payments Property taxes Heating costs Condo fees (if applicable) Many lenders prefer a GDS ratio below 39%. Total Debt Service (TDS) TDS includes all monthly debt obligations in addition to housing expenses. This includes: Credit card payments Student loans Car loans Personal loans Most lenders prefer a TDS ratio below 44%. If your debt ratios are too high, lenders may worry that taking on a mortgage could create financial strain. How Different Types of Debt Affect Mortgage Approval Not all debt affects your mortgage application the same way. Some forms of debt are viewed more favourably than others. Credit Card Debt Credit card debt can be one of the biggest concerns for mortgage lenders because it usually carries: High interest rates Revolving balances Variable monthly payments High credit card balances may: Lower your credit score Increase your TDS ratio Reduce borrowing power Keeping balances low before applying for a mortgage can significantly improve your approval chances. Student Loans Student loans are very common among Canadian borrowers, especially first-time homebuyers. Lenders generally view student debt more positively because: Payments are structured Interest rates may be lower Borrowers often have future earning potential However, lenders still include student loan payments when calculating your debt ratios. Auto Loans Car loans are easier for lenders to evaluate because they involve fixed monthly payments and repayment schedules. While auto loans still affect your borrowing capacity, they are generally considered less risky than revolving debt. Lines of Credit Lines of credit may impact mortgage approval even if you are not actively using the full balance. Lenders may consider: Your available credit limit Minimum payment estimates Existing balances Managing your line of credit responsibly is important when preparing for a mortgage application. Also read: Commercial vs. Residential Mortgages: What’s the Difference? How to Improve Your Mortgage Approval Chances If you currently have debt, there are still several ways to strengthen your mortgage application. Pay Down High-Interest Debt Reducing high-interest debt, especially credit cards, can improve both your credit score and debt ratios. Focusing on paying down revolving debt may: Lower monthly obligations Improve lender confidence Increase borrowing capacity Even small balance reductions can positively affect your application. Improve Your Credit Score A stronger credit score can improve both mortgage approval chances and interest rates. To strengthen your score: Make payments on time Keep balances below 30% of credit limits Avoid missed payments Limit new credit applications Consistency
Commercial vs. Residential Mortgages: What’s the Difference?
Buying property is one of the biggest financial decisions people make, whether it is a family home or an investment building. However, not all mortgages work the same way. One of the most common questions borrowers ask is: What is the difference between commercial and residential mortgages? Understanding these two types of financing is important because each comes with different requirements, interest rates, approval processes, and risks. If you are planning to buy a home, rental property, office space, retail unit, or investment building in Canada, knowing how commercial vs. residential mortgages work can help you make smarter financial decisions. Here, we will explain the key differences, benefits, and factors lenders consider before approving each type of mortgage. What Is a Residential Mortgage? A residential mortgage is a loan used to purchase or refinance a property intended for living purposes. These mortgages are commonly used for: Single-family homes Condominiums Townhouses Duplexes Small rental properties with up to four units Residential mortgages are designed for individuals or families who want to buy a home. In Canada, most homebuyers use residential mortgages because they offer lower down payments and generally lower interest rates compared to commercial financing. Lenders usually assess a borrower’s personal income, employment history, credit score, debt levels, and financial stability before approving a residential mortgage. Common Features of Residential Mortgages Some common characteristics include: Lower down payment requirements Fixed or variable interest rate options Longer amortization periods Easier qualification process Government-backed mortgage insurance options Residential mortgages are often considered less risky for lenders because people prioritize paying for their homes before other debts. What Is a Commercial Mortgage? A commercial mortgage is used to finance properties that are intended for business or investment purposes. These properties may generate income or support business operations. Commercial mortgages are commonly used for: Office buildings Retail stores Industrial properties Apartment complexes with five or more units Warehouses Mixed-use buildings Restaurants and hotels Unlike residential loans, commercial mortgages focus heavily on the property’s income-generating potential. Lenders evaluate whether the property can produce enough revenue to cover mortgage payments and operating expenses. Commercial mortgages are generally more complex because they involve larger loan amounts, higher risks, and stricter qualification requirements. Commercial vs. Residential Mortgages: Major Differences Although both mortgage types help finance real estate purchases, there are several important differences between them. Property Type The biggest difference lies in the type of property being financed. Residential mortgages are for homes and small residential properties where people live. Commercial mortgages are for business-related or income-producing properties. For example: Buying a family home requires a residential mortgage. Buying an office building requires a commercial mortgage. A residential rental property with one to four units usually falls under residential financing, while apartment buildings with five or more units are typically considered commercial properties. Down Payment Requirements Commercial mortgages usually require a much larger down payment than residential mortgages. For residential properties in Canada, buyers may qualify with as little as 5% down, depending on the purchase price and mortgage insurance eligibility. Commercial properties often require: 20% to 35% down payment Higher cash reserves Additional financial documentation This is because commercial lending is considered riskier for banks and lenders. Interest Rates Interest rates for commercial mortgages are usually higher than residential mortgage rates. Residential mortgage rates tend to be lower because the loans are considered more stable and less risky. Commercial properties, on the other hand, may be affected by market fluctuations, tenant vacancies, or business performance. Commercial rates may vary depending on: Property type Business financial health Tenant stability Market conditions Loan size Even a small difference in interest rates can significantly impact monthly payments on large commercial loans. Also read: Can You Buy a House with 5% Down in 2026? Mortgage Approval Process Residential mortgage approvals focus mainly on the borrower’s personal finances. Lenders review: Employment history Credit score Debt-to-income ratio Personal income Savings and assets Commercial mortgage approvals are more detailed and complex. Lenders analyze: Business income Property revenue Lease agreements Cash flow projections Net operating income Business credit history The property itself plays a major role in the approval process because lenders want assurance that it can generate enough income to support the loan. Loan Terms and Amortization Residential mortgages often offer longer amortization periods, sometimes up to 25 or 30 years. This helps keep monthly payments lower for homeowners. Commercial mortgages generally have: Shorter loan terms Higher monthly payments Shorter amortization schedules Commercial lenders may offer terms ranging from 5 to 20 years, depending on the property and borrower profile. Mortgage Insurance Residential borrowers in Canada may qualify for mortgage insurance through institutions like CMHC if their down payment is less than 20%. Commercial mortgages do not usually have the same type of government-backed mortgage insurance available. As a result, lenders often require larger down payments and stricter conditions. Flexibility and Risk Commercial mortgages carry more risk because business income can fluctuate due to economic conditions, tenant turnover, or market demand. Residential mortgages are generally considered more predictable because people prioritize housing payments even during financial challenges. Because of this difference in risk: Commercial loans have stricter approval criteria Residential loans are easier for average borrowers to obtain Which Mortgage Is Easier to Qualify For? Residential mortgages are typically easier to qualify for because the process is more standardized and supported by government-backed lending programs. Commercial mortgages can be more difficult because lenders require: Strong business plans Stable income projections Larger financial reserves Higher down payments Borrowers seeking commercial financing often need professional financial statements and detailed documentation before approval. Benefits of Residential Mortgages Residential mortgages offer several advantages for homebuyers and small property investors. Lower Down Payments: Many buyers can enter the housing market with smaller upfront costs. Lower Interest Rates: Residential financing generally provides more affordable borrowing costs. Longer Repayment Periods: Long amortization periods help reduce monthly payment amounts. Easier Approval Process: Borrowers with stable income and reasonable credit scores often qualify more easily. Benefits of Commercial Mortgages Commercial mortgages also
How Long Do You Need to Be Self-Employed to Get a Mortgage in Canada?
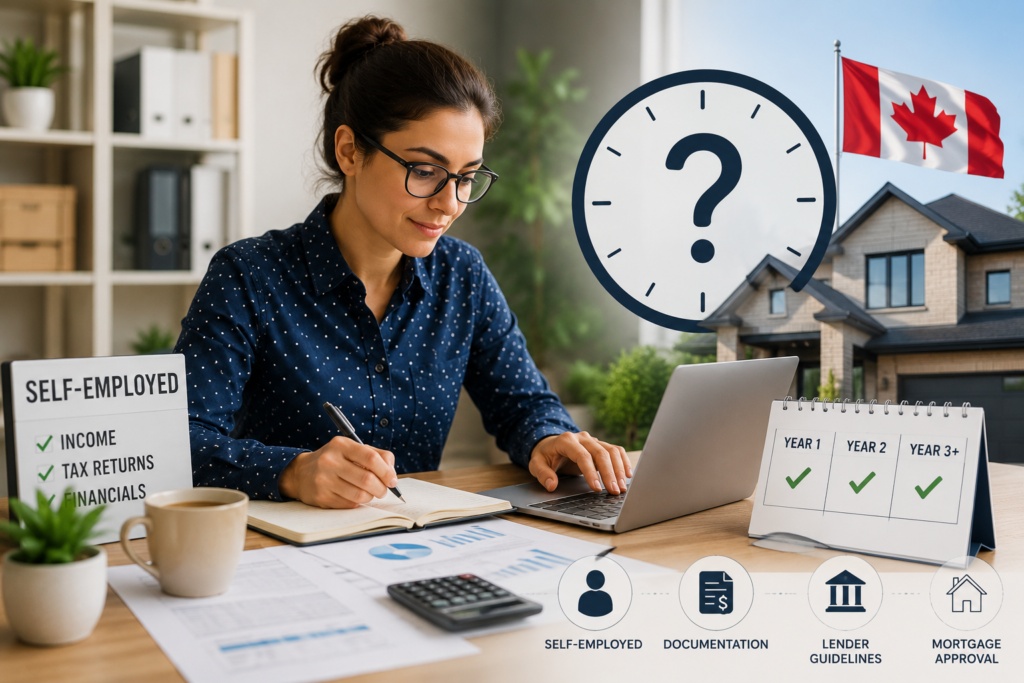
Buying a home is an exciting milestone, but if you’re self-employed, the mortgage process may feel more complicated than it does for salaried employees. Many Canadian entrepreneurs, freelancers, contractors, and small business owners wonder whether they can qualify for a mortgage and how long they need to be self-employed before lenders will consider their application. The good news is that being self-employed does not prevent you from getting approved for a mortgage. However, lenders typically require additional documentation to verify your income and assess your financial stability. Understanding these requirements can help you prepare and improve your chances of approval. Can Self-Employed Individuals Get a Mortgage in Canada? Yes, self-employed Canadians can qualify for mortgages through banks, credit unions, and alternative lenders. Whether you’re a freelancer, consultant, contractor, sole proprietor, or business owner, there are mortgage solutions available. The main difference is that lenders often view self-employed income as less predictable than traditional employment income. As a result, they usually conduct a more detailed review of your finances before approving a mortgage. Generally, lenders want to see that your business generates consistent income and that you can comfortably manage monthly mortgage payments. How Long Do You Need to Be Self-Employed to Qualify for a Mortgage? For most traditional lenders in Canada, two years of self-employment history is considered the standard requirement. During the application process, lenders often review: Two years of personal tax returns Two years of Notices of Assessment (NOAs) Business financial statements Business bank records Additional proof of income when necessary The two-year benchmark helps lenders evaluate whether your income is stable and sustainable. Can You Get a Mortgage With One Year of Self-Employment? In some cases, yes. Certain lenders may approve borrowers with only one year of self-employment history, especially if they can demonstrate: Previous experience in the same industry Strong annual income Excellent credit history Significant savings A larger down payment Ongoing client contracts or predictable revenue For example, if you worked as an employee in a profession for several years before becoming an independent contractor, some lenders may consider your prior experience when assessing your application. Also read: Can You Get A Mortgage With Debt in Canada? What If You’ve Been Self-Employed for Less Than One Year? Obtaining a mortgage becomes more challenging with less than one year of self-employment history, but it is not impossible. Alternative lenders and private lenders may offer financing options if you can provide strong supporting documentation and demonstrate your ability to manage mortgage payments. However, these solutions may come with higher interest rates and fees compared to traditional mortgages. What Documents Do Self-Employed Mortgage Applicants Need? Because self-employed income can vary from year to year, lenders typically require more documentation than they do for salaried applicants. Common documents include: Personal Tax Returns Most lenders request the last two years of T1 General tax returns to verify income history. Notices of Assessment Your Notices of Assessment from the Canada Revenue Agency help confirm that your taxes have been filed and that there are no outstanding issues. Business Financial Statements If you own a business, lenders may ask for financial statements prepared by an accountant. Business Bank Statements These statements help verify cash flow and business activity. Articles of Incorporation If your company is incorporated, lenders may request incorporation documents. GST/HST Returns Some lenders use GST/HST filings to help validate business revenue. Having organized financial records can significantly improve the mortgage approval process. How Do Mortgage Lenders Calculate Self-Employed Income? One of the most common questions self-employed borrowers ask is how lenders determine their qualifying income. In many cases, lenders average your income over the previous two years. This helps account for fluctuations in revenue and provides a more accurate picture of your earning capacity. However, lenders may use different methods depending on your situation. Average Income Method If your income has remained relatively stable, lenders may calculate an average based on the last two years of reported earnings. Income Trend Analysis If your income has been steadily increasing, some lenders may place greater emphasis on your most recent earnings. Business Expense Add-Backs Certain lenders may add back specific business expenses when evaluating income. This can be beneficial for self-employed borrowers who use legitimate tax deductions that reduce their reported net income. Mortgage Options for Self-Employed Canadians Self-employed borrowers have several mortgage options available. Traditional Banks Major banks typically offer competitive mortgage rates but often have stricter qualification requirements. Credit Unions Credit unions may provide greater flexibility when assessing self-employed income. Alternative Lenders Alternative lenders often work with borrowers who have shorter self-employment histories or more complex income situations. Private Lenders Private lenders can provide financing when traditional options are unavailable, though interest rates are generally higher. Working with an experienced mortgage broker can help you identify the most suitable lender for your circumstances. What Credit Score Do Self-Employed Borrowers Need? Credit score plays an important role in every mortgage application. While requirements vary by lender, many traditional lenders prefer a credit score of at least 680 or higher. A stronger credit score can help you: Qualify for better mortgage rates Access more lending options Improve approval chances Reduce borrowing costs over time If your credit score needs improvement, consider paying bills on time, reducing debt balances, and correcting any errors on your credit report before applying. How Much Down Payment Is Required? Self-employed borrowers generally follow the same minimum down payment rules as other Canadian homebuyers. Current minimum down payment requirements include: 5% for the first portion of the home’s purchase price within eligible limits Additional amounts depending on the home’s value and applicable mortgage regulations However, many self-employed borrowers benefit from providing a larger down payment. A larger down payment can: Reduce lender risk Increase approval chances Lower monthly mortgage payments Potentially secure better lending terms Also read: Why Real Estate Investors Need A Strategic Mortgage Broker Common Challenges Self-Employed Borrowers Face While many self-employed Canadians successfully obtain mortgages, there are some common obstacles. Tax Deductions Reducing Income